

Risk Management · 2025
In this section3 topics
Risk Management Policy & Plan
Policy & Plan Description
The company recognizes the importance of risk prevention in its business of developing real estate for sale, for rent, and providing comprehensive residential services, as this business may be affected by various internal and external risk factors. Therefore, the company assesses risk factors and implements risk prevention measures in all aspects, including studying consumer behavior and the needs of target customer groups in terms of location, project type, house design, and price levels, among others. Research is conducted both before and during project implementation to effectively reduce risks from changes in consumer behavior, minimize sales forecast discrepancies, reduce liquidity problems, and ensure the company's investment is utilized efficiently in project development.
The company recognizes and values good corporate governance to drive organizational growth and stable business expansion, maintain a strong financial position, and generate appropriate returns for shareholders. The Board of Directors has appointed a Risk Management Committee, comprising independent directors and executives, and has established a risk management policy, duties, and responsibilities for managing risks, preventing, reducing risks, or effectively mitigating potential impacts. The Risk Management Committee has appointed a Risk Management Control, Monitoring, and Coordination Working Group to oversee the assessment process and monitor the results of identified risks. Furthermore, the company places importance on preventing corruption. The company has established a policy for compliance with anti-corruption laws and conducts continuous annual corruption risk assessments. A policy for preventing involvement in corruption has been defined and included in the company's Corporate Governance Policy and Business Ethics Handbook, which has been published on the company's website.
Operational Framework
The Company has established a risk management policy aimed at developing a comprehensive risk management system in accordance with the principles of good corporate governance. The policy ensures that risk management covers all dimensions of risk across the organization. A Risk Management Committee has been appointed to oversee the Company’s risk management processes, ensuring that risks are managed in line with the Company’s objectives and maintained at an acceptable level. The Committee is also responsible for formulating the risk management policy to be implemented across all business units, including the development of strategies and the assessment of risk factors. The Company evaluates both external and internal risk factors, covering all key areas, including strategic, operational, financial, compliance, and event-related risks, as well as risks associated with fraud and corruption. Risk factors, both internal and external, that may impact the organization are reviewed on an annual basis.
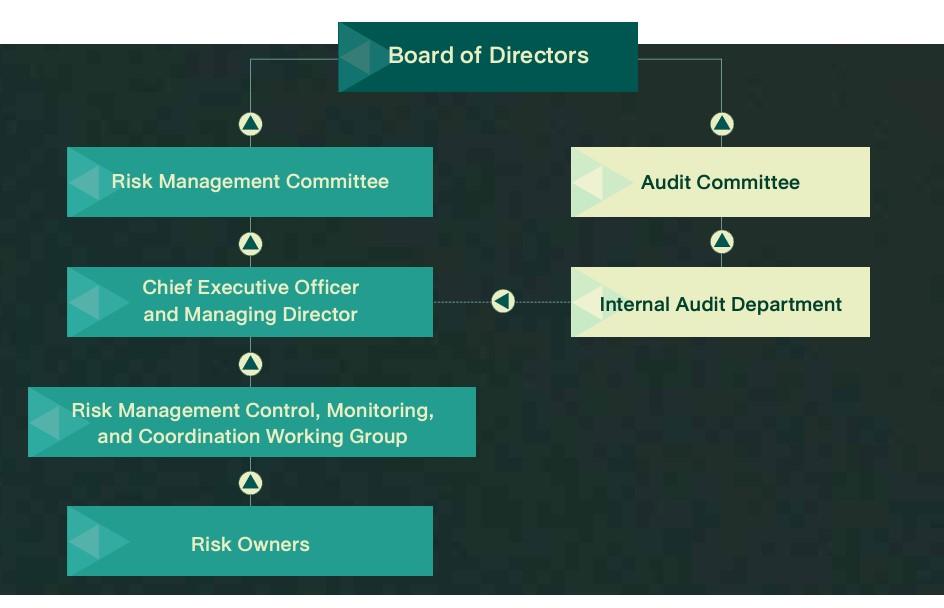
The risk management structure and roles and responsibilities in risk management are as follows:
Board of Directors
Responsible for setting policies, strategic directions, and overseeing an effective risk management system. The Board of Directors has approved the establishment of a Risk Management Committee to define the company's risk management operational framework, including policies, structure, roles, duties, and responsibilities of those involved in risk management activities, and to oversee potential risks to the company, covering various risk aspects, including climate change oversight, to help the company achieve its stated objectives and goals in the coming year. In the year 2025. To ensure the company's risk management operations are effective, the Board of Directors regularly monitors, acknowledges, provides recommendations, and oversees risk management operations through reports from the Risk Management Committee.
Audit Committee
Comprises 4 independent directors, responsible for overseeing and auditing risk management within the organization, focusing on reviewing internal control systems (Internal Control) and compliance with relevant policies. This ensures that the company's internal control systems are appropriate and sufficient to manage operations in line with goals, objectives, laws, and regulations consistent with the guidelines of the SEC and the Stock Exchange of Thailand. It also involves considering accurate and reliable financial reports with complete and sufficient disclosure to enhance confidence in the organization's audit and risk management processes effectively.
Risk Management Committee
Comprises 8 directors, with 1 independent director serving as the Chairman of the Risk Management Committee, responsible for Organizational risk management, which will oversee specific and clearly defined risks and operate systematically, covering economic, social, and environmental risks. The Board of Directors has approved the establishment of a Risk Management Committee to define the framework.
The company's risk management operations, including defining policies, structure, roles, duties, and responsibilities of those involved in risk management activities, and overseeing potential risks to the company, to help the company achieve its stated objectives and goals. In the year In 2025, the Risk Management Committee held 4 meetings to consider and monitor risk management. Risk information was reported to the Board of Directors to ensure effective risk operations.
Chief Executive Officer and Managing Director
Responsible for establishing a risk management system in accordance with the policies and guidelines set by the Board, considering and defining strategies, and ensuring the implementation and monitoring of enterprise-wide risk management to cover significant risks, including business operations risks, sustainability risks, and climate risks. It also involves communicating and developing an organizational culture that is aware of risks, as well as reviewing the suitability of systems and measures to adapt to changes in business, regulations, and relevant legal requirements.
Risk Management Control, Monitoring, and Coordination Working Group
Comprises executives representing various departments, responsible for proposing risk management operational plans, coordinating with various departments to monitor and assess identified risks, and managing risk data to reduce it, reporting the results to the Risk Management Committee. including implementing resolutions from the Risk Management Committee relevant to the departments and closely reporting on the monitoring results of risk management.
Internal Audit Department
Responsible for auditing and reviewing operational processes to ensure compliance with policies, rules, regulations, and relevant practices, to ensure the company's internal control systems are appropriate, and to report to the Audit Committee for submission to the Board of Directors.
Risk Owners
Responsible for identifying, analyzing, and assessing risks, and preparing risk management plans at an acceptable level, to be submitted to the Risk Management Control, Monitoring, and Coordination Working Group.
Risk Management Process
Defining Objectives (bjective Setting)
Defining Risk Rating Scale and Risk Appetite, including Risk Tolerance.
Risk Identification
Risk Assessment
Risk Response
Monitoring and Reporting of Risk Management Results (Motoring and Report)
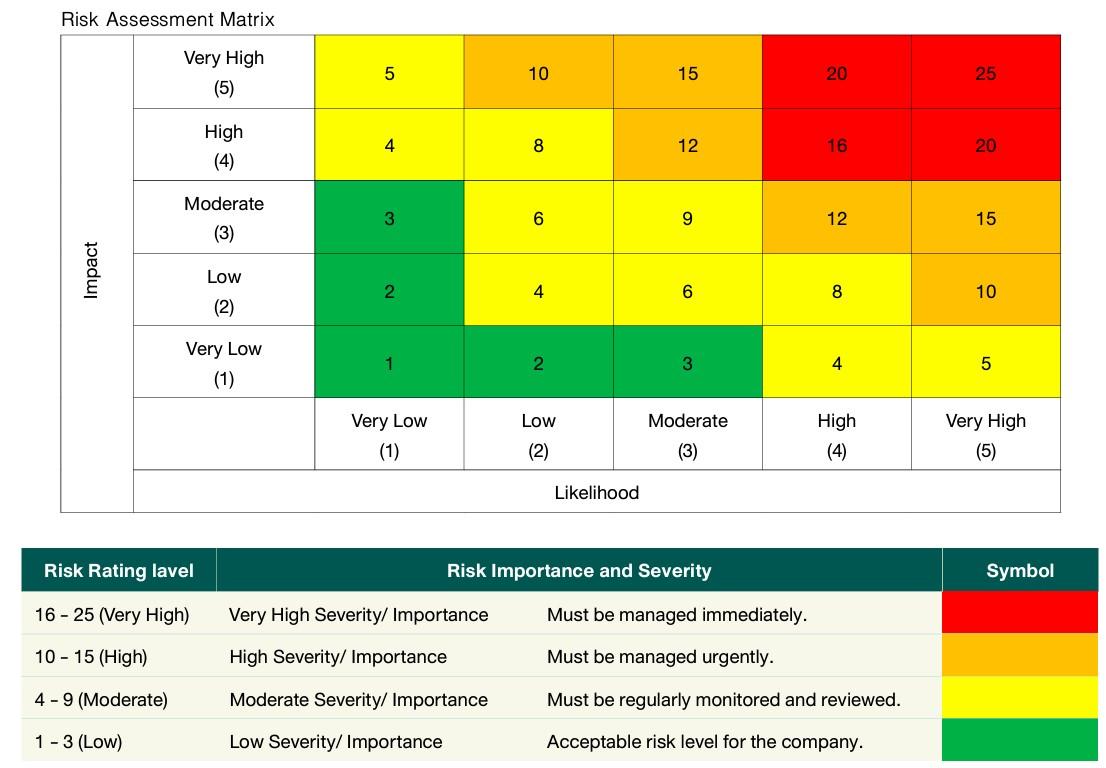
In this regard, the company has defined acceptable risk levels under Risk Assessment by Acceptable Risk Level (Risk Appetite) is the risk that has been assessed to be at Low level is considered an acceptable risk level, but controls are in place to prevent the risk level from escalating, and there is a defined Risk Tolerance Level is the risk that deviates flexibly from acceptable criteria. (score not exceeding 15 points) where the company's risk management operations are within acceptable criteria and do not cause significant impact. For risk levels exceeding the company's acceptable risk appetite (Exceeding Risk Appetite), this refers to risks assessed at a level from medium to extreme.
Policy Document Link
https://www.sena.co.th/content/files/%e0%b8%81%e0%b8%b2%e0%b8%a3%e0%b8%81%e0%b8%b3%e0%b8%81%e0%b8%b1%e0%b8%9a%e0%b8%94%e0%b8%b9%e0%b9%81%e0%b8%a5%e0%b8%81%e0%b8%b4%e0%b8%88%e0%b8%81%e0%b8%b2%e0%b8%a3/2025/Apr/en/7_SENA_Enterprise-Wide-Risk-Management-Policy-21-1-2568.pdf
Page Number in Report
1-3
Risk Factors — Overview
Risk Factors — Introduction
Organizational Risk Management Culture.
To promote awareness, understanding, and practices related to risk management at all levels of the organization, ensuring that everyone in the organization participates in recognizing risks and knowing how to effectively manage them. A good risk management culture can help the organization face risks stably and sustainably.
The company therefore promotes the development of Risk awareness. By providing training to employees to familiarize them with the risks the organization may face, whether financial risks, operational risks, or risks from external factors. Effectively communicate significant risks and risk management methods to all employees in the organization. Focus on The participation of everyone in the organization. By raising awareness of their role in risk management and fostering an understanding of their roles and responsibilities in identifying and managing risks related to employees' work. Promoting responsible decision-making. Decisions should be made considering the potential impact of risks, and long-term impact analysis must be conducted under careful and appropriate risk consideration. Management emphasizes risk management by supporting and promoting risk management, with mechanisms in place for organizational risk management. Continuous evaluation and improvement are conducted. By regularly monitoring and evaluating the effectiveness of risk management operations to ascertain whether the measures implemented are appropriate and efficient. Ultimately, fostering a strong risk management culture will enable the organization to effectively manage various risks, mitigate potential adverse impacts, and build long-term sustainability for the organization.
The company continuously monitors various situations across economic, social, and environmental dimensions that tend to be risk factors with the potential to impact the organization, including risks affecting current business operations and new risks emerging in the next 3-5 years. The company has defined acceptable risk levels and risk indicators, which have been approved by the Risk Management Committee. The results of these risk factor assessments are then used to develop an appropriate risk management development plan.
For effective risk management, the company has organized meetings and monitored organizational risks through the Risk Management Control, Monitoring, and Coordination Working Group. This group tracks the assessment process and monitors the results of risk management activities every quarter, and presents reports on key issues to the Risk Management Committee for consideration and submission to the Board of Directors for acknowledgment and further recommendations.
This year, from monitoring risk assessments, it was found that the company has fully implemented the planned initiatives. The company continues to monitor risk issues arising from internal and external factors to ensure that most of the company's risks are reduced or maintained at an acceptable level.
Risks to the Company's Business Operations
Risk Register
| Risk Name | Risk Characteristics | Consequences | Management Measures | Related Risk Factors |
|---|---|---|---|---|
| Competitive Risks in Real Estate Development Business | As of the end of 2025, the remaining supply in the housing market stood at approximately 239,168 units, with a total value of approximately 1,341,313 million Baht, which increased by about 2-5% from the previous year, due to demand factors that have not fully recovered and a slowdown in public sales. Divided into main categories, namely:
The real estate market in this area remains highly competitive. There are hundreds of operators, including those listed on SET/MAI and small companies. Therefore, no single operator can definitively dictate prices and quantities in the market. Buyers have many options and can easily compare products through online channels and various housing exhibitions. | The real estate market, whether residential or commercial, cannot be considered solely as a whole. It requires segmentation by area and price level, because a good market for one developer may not be a good market for another, and a good location or price for one consumer may not be a good location or price for another. Therefore, the company thoroughly conducts market data analysis and feasibility studies at the local level every time before commencing investment. Competition in the real estate market therefore requires in-depth insights from market research, both broad and specific, for each area, each type of property, and each price level. The company continuously conducts such market research. Feasibility studies are conducted for each project development, from preliminary studies to thorough and detailed analyses, covering financial, marketing, design aspects, etc. We are therefore confident in developing projects and meeting market demands according to current trends and future prospects. The company maintains a strong and active collaboration with Hankyu Hanshin Properties Group from Japan, who have been business partners for over 9 years. This partnership helps promote the development of high-quality and high-standard residential projects. The company can control competitive risks by differentiating itself through seeking new opportunities, such as considering diversifying into real estate sectors related to public health and elderly care, which aligns with the concern for public health; seeking opportunities in new areas and quickly acquiring land in suitable locations; responding to customer needs at desired price points, consistent with purchasing power and travel conditions; studying other innovations that can be extended to the real estate development business; developing various applications; and continuous personnel development to create and develop the best products and services for customers. Furthermore, the company can seamlessly expand into businesses related to the real estate sector, such as solar energy businesses, which can be applied to residential and commercial properties, warehouse businesses, project management businesses, real estate brokerage businesses, golf course businesses, etc. | 728 · Description: Volatility in the industry in which the company operates · Info category: STRATEGIC_RISK · 729 · Description: Behavior or needs of customers / consumers · Info category: STRATEGIC_RISK · 730 · Description: Government policy · Info category: STRATEGIC_RISK | |
| Risk of contractor and labor shortage | Thailand continues to face a persistent labor shortage in the construction sector, particularly for skilled labor and construction workers in urban and suburban areas. This has led real estate development businesses to rely increasingly on labor from neighboring countries. Concurrently, the government's continuous investment in transportation infrastructure and public utility projects has driven up the demand for labor in the construction sector, which may result in a shortage of labor and contractors during certain periods. | Labor and contractor shortages may result in prolonged project construction periods, increased labor wages and construction costs, and could also affect the ability to control costs and deliver projects according to the planned schedule. Furthermore, the continuous adjustment and increase of minimum wage rates, particularly in Bangkok and its vicinity, may lead to higher labor costs for operators and impact the overall cost structure of real estate development projects. | The Company places importance on systematically managing risks related to contractors and labor. This is achieved by selecting qualified contractors who meet the Company's specified standards, while also fostering long-term cooperation through continuous engagement to enhance stability in construction project execution. Furthermore, the Company has established appropriate work plans and construction timelines. Progress is closely monitored and controlled, including the establishment of terms and penalties for late project delivery, to help mitigate construction timeline risks, control costs, and reduce the impact of labor fluctuations. Concurrently, the Company has prioritized the management of emerging risks (Emerging Risks) arising from changes in labor structure, government policies, and the business environment. This involves continuously reviewing and improving guidelines for managing contractors and labor, as well as elevating work standards and applying appropriate technology to enhance construction efficiency and address long-term challenges. | 739 · Description: Shortage or reliance on skilled workers · Info category: OPERATIONAL_RISK · 730 · Description: Government policy · Info category: STRATEGIC_RISK |
| Risk from land acquisition for future project development | Land for residential development in suitable locations, at appropriate prices, and of suitable sizes is becoming an increasingly scarce resource. It is either starting to become scarce or is available only at prices too high to develop projects that meet the company's target audience in each location. Competition in the real estate business has intensified, leading to increased competition among developers for land acquisition, particularly in prime locations in central Bangkok or areas along mass transit routes. This may expose the company to risks related to the inability to procure and acquire land according to its business plan. Furthermore, rising land prices impact project development costs and may prevent the development of projects that yield returns in line with investment plans. | The Company holds undeveloped land (Land Bank) that is not yet ready for project development. This arises either from business acquisitions that included undeveloped or incomplete land development, or from land acquired in the past and held for future project development. However, given that land is a high-value asset requiring significant investment, and project development typically takes at least one year per project, depending on its size. Investing in land acquisition in advance without a development plan for that area carries the risk of reduced liquidity, preventing the capital from being used for working capital or other project developments. It also increases project development costs due to the financial expenses incurred in purchasing the land. Furthermore, the land tax burden as per legal requirements must also be taken into account. However, the Company has a comprehensive plan for land acquisition for project development, which includes defining annual land sourcing guidelines and considering target areas and land prices that offer high returns on investment and align with the type and price level of the real estate projects to be developed. This ensures a continuous supply of land for project development. For each potential land acquisition, a preliminary feasibility study for project development is conducted, evaluating the opportunities and potential from developing such land, the growth direction of residential areas, the development routes of rail mass transit projects, legal restrictions, and a thorough title deed verification. This comprehensive process aims to mitigate all risks before making a land purchase decision. | Market studies are regularly conducted to assess trends and potential for residential development in each area, aiming to mitigate risks arising from increasing land prices, the risk of being unable to acquire locations with future development potential, or risks from changing government policies, such as land and building taxes and the planning of rail mass transit projects. In addition, the company procures land by purchasing directly from landowners, a process handled internally by the relevant department under clearly defined land acquisition procedures, and also through brokers, with whom the company maintains good relationships with several land acquisition brokers, enabling continuous land acquisition for future real estate development projects. | 762 · Description: Change in financial and investment policies of financial institutions that affect business operations · Info category: FINANCIAL_RISK · 730 · Description: Government policy · Info category: STRATEGIC_RISK |
| Regulatory and Legal Risks | Impact from changes in legal regulations and operational procedures for the real estate business. There are several related rules, regulations, or laws, such as the Land Allocation Act, the Condominium Act, and the National Environmental Quality Promotion and Protection Act, etc. In the past, the Company has had a clear policy to operate in compliance with relevant laws and regulations and has prepared for newly issued regulations, studying the impacts, advantages, and disadvantages of various regulations to maximize benefits for the Company and all stakeholder groups. The enactment of the Personal Data Protection Act B.E. 2562 (2019), which came into effect on June 1, B.E. 2565 (2022). This law directly impacts business operations, as data is considered a type of asset in the operations of all organizations. For instance, personal data of employees, business partners, and especially customers, carries a risk of violating the regulations under the Personal Data Protection Act if there are no secure personal data management measures in place. | may cause project delays, incur additional costs, or prevent the project from being executed as planned, impacting revenue, operating results, and stakeholder confidence, and may also lead to fines or legal proceedings. | For the company, acting as a data controller, various policies related to the Personal Data Protection Act (PDPA) have been established. These include defining personal data security measures, establishing operational procedures compliant with legal requirements from the initial stage of data acquisition for business use, data storage and retention, and providing training to ensure a comprehensive understanding of the law's essence and correct practices for employees directly involved with customer and partner personal data. Additionally, an understanding of the Personal Data Protection Act is communicated to all employees within the organization to foster awareness and caution in the use of personal data. | 756 · Description: Change in laws and regulations · Info category: COMPLIANCE_RISK |
| Housing Loan Credit Policy Risk of Financial Institutions | Risks in housing loan policies of financial institutions stem from the slowing economic conditions, Thailand's high household debt burden, and the uncertainty of public income. This has led financial institutions to be more stringent in approving loans. Data from 2024–2025 reflects that housing loans in the commercial banking system grew by only approximately 1–2 percent per year, which is the lowest level in over 20 years. Although the Bank of Thailand implemented measures to relax Loan-to-Value (LTV) criteria starting in 2025 to support greater access to credit, financial institutions continue to prioritize assessing borrowers' debt repayment ability. | Stricter credit approval may prevent residential buyers, particularly middle-income groups and first-time homebuyers, from accessing credit as needed. This could lead to a slowdown in property transfer rates and sales of real estate projects, potentially impacting the company's revenue, cash flow, and ability to manage inventory. Furthermore, the project sales period may lengthen, and the company may need to implement additional sales promotion measures or financial conditions, resulting in a decrease in the company's profit margins at certain times. | The company also implements measures to screen retail buyers, or pre-approval for booking housing estates or condominiums, to mitigate issues of purchase cancellations due to unsuccessful loan applications and to minimize lost sales opportunities. Furthermore, the company coordinates with financial institutions, including both commercial and state-owned banks, to closely monitor the lending policies of each institution and to adapt its credit management approach for residential buyers to align with each financial institution's policies at various times. Additionally, the company has launched the “Rent-to-Save Home – LivNex” project, an innovation developed to address the challenges of customers in the mid-to-lower market segments who currently lack sufficient eligibility to secure direct loans from financial institutions. This program allows them to rent and save simultaneously, thereby enabling them to eventually acquire full ownership of the property. | 728 · Description: Volatility in the industry in which the company operates · Info category: STRATEGIC_RISK · 758 · Description: Violations of laws and regulations · Info category: COMPLIANCE_RISK |
| Risks from the fluctuation of construction material costs and minimum wage costs | Key factors in the company's business operations include construction costs, which, in addition to land acquisition costs, represent a significant risk factor impacting the company's business. Construction costs primarily comprise material costs and labor costs. The prices of construction materials fluctuate according to global supply and demand, economic growth, inflation rates, domestic construction conditions, and adjustments to the minimum wage. This creates a risk of potentially higher construction costs in the future, particularly in the steel and steel products category, which has seen significant increases in line with rising global steel prices. Furthermore, prices for various construction materials, such as electrical and plumbing equipment, concrete products, and other construction materials, may increase due to rising raw material costs, crude oil prices, and transportation expenses, especially if geopolitical tensions affect key manufacturing countries. | Fluctuations in construction material costs and labor wages may result in project costs exceeding estimates, leading to a reduction in gross profit margins and potentially affecting the ability to set competitive selling prices in the market. Furthermore, if costs increase rapidly during construction, some projects may require work plan adjustments, experience delivery delays, or necessitate a reduction in certain specifications. This could impact customer satisfaction and the company's image. | The company manages risks by carefully planning costs in advance, utilizing long-term material procurement contracts or lump-sum contracts with contractors to mitigate risks from price fluctuations. This also includes selecting cost-effective technologies and alternative materials without compromising construction quality. Furthermore, the company enhances the efficiency of construction processes and closely monitors labor costs to maintain profitability and long-term competitiveness. | 728 · Description: Volatility in the industry in which the company operates · Info category: STRATEGIC_RISK · 730 · Description: Government policy · Info category: STRATEGIC_RISK · 750 · Description: Climate change and disasters · Info category: OPERATIONAL_RISK · 751 · Description: Impact on the environment · Info category: OPERATIONAL_RISK |
| Liquidity risk and access to funding sources | The real estate development business is a capital-intensive business, starting from land acquisition, land development, construction, and sales. All these activities require substantial capital investment until the company receives the majority of the sales value on the transfer of ownership date, which occurs upon completion of construction. The company typically manages projects for approximately 1-2 years or more, depending on the project size. Therefore, this business carries risks related to financial liquidity management and access to funding sources required for business operations. | If the company is unable to manage liquidity adequately or access funding sources as planned, this could result in project development delays, new investments being postponed, or the necessity to rely on higher-cost funding sources. This would impact cash flow, debt repayment capability, and project returns. Furthermore, it could affect investor and financial institution confidence in the long term. | The company has implemented a policy to increase liquidity in accessing funding sources by establishing business partnerships with several financial institutions, and has consistently received strong credit support from these trusted institutions. The company will compare offers to select the most cost-effective options for project development loans (Pre-Finance) by the company. Pre-Finance credit lines are available for all projects. The company also utilizes fundraising to manage liquidity by issuing short-term bills and both short-term and long-term debentures, tailored to funding needs for project development and business expansion. These debenture issuances have been well-received by the market due to the company's reputation and business experience. Furthermore, the company prioritizes financial liquidity management by conducting business with careful consideration in project development, which includes selecting land locations for investment, conducting research to analyze the feasibility of various projects, and emphasizing the details of all critical aspects in each project to ensure the success of every project. Strong and active cooperation with Hankyu Hanshin Properties Group from Japan, a long-standing business partner for over 9 years, also helps enhance financial potential for even stronger growth. Furthermore, the Board of Directors has a clear policy on capital management, which includes risk management. In terms of financial management, to mitigate risks that could impact the company's operations and financial position, there is supervision and monitoring to ensure management continuously reports operational results. Additionally, contingency plans are in place for potential financial difficulties, with due consideration for fairness to all stakeholders equally. This also includes ensuring liquidity management to ensure readiness for timely debt repayment to creditors under emergency situations, enabling debt repayment even during liquidity crises. Should the company be unable to comply with agreed-upon terms, the company will inform creditors and proceed to find solutions, as well as ensure that accurate and complete information is reported to creditors. | 762 · Description: Change in financial and investment policies of financial institutions that affect business operations · Info category: FINANCIAL_RISK · 764 · Description: Fluctuation in exchange rates, interest rates, or the inflation rate · Info category: FINANCIAL_RISK · 765 · Description: Fluctuation in return on assets or investment · Info category: FINANCIAL_RISK |
| Financial risk from increasing interest rates | Financial risk from rising interest rates stems from the company's necessity to utilize both short-term and long-term loan sources for project development, including the issuance of debentures or borrowing from financial institutions. Interest rates fluctuate according to economic conditions and the central bank's monetary policy. Should interest rates increase, it will directly result in higher financial costs for the company. | The upward adjustment of interest rates may lead to an increase in the company's interest expenses, affecting net profit and operating cash flow. Furthermore, it could diminish the ability to set competitive prices for residential properties and indirectly impact customer purchasing power due to increased mortgage repayment burdens, which may result in a decrease in purchase decisions and property transfer rates. | The company prioritizes systematic interest rate risk management. This involves establishing policies to manage the capital structure appropriately and in line with the nature of the real estate development business, which requires long-term investment. The company diversifies its funding sources, including loans from financial institutions, bond issuance, and the use of internal working capital, to avoid over-reliance on any single funding source. Furthermore, it manages the proportion of fixed-rate and floating-rate loans in an appropriate ratio to mitigate the impact of interest rate fluctuations in the market. Additionally, the company plans its borrowings in alignment with the development plans and revenue recognition of each project, including carefully considering the debt structure and repayment periods to maintain appropriate liquidity and debt-servicing capacity. The company closely monitors macroeconomic conditions and the monetary policy direction of the Bank of Thailand to inform financial and investment decisions appropriately at each given time. In terms of business operations, the company manages project costs in conjunction with financial management. This involves considering appropriate selling prices, sales launch strategies, and project development timing to align with market conditions and changing financial costs. This also includes collaborating with business partners and financial institutions to develop financial products and credit terms that facilitate customer purchasing decisions, which helps reduce the impact of increased interest burdens on both the company and homebuyers. | 761 · Description: Insufficient sources of funding · Info category: FINANCIAL_RISK · 762 · Description: Change in financial and investment policies of financial institutions that affect business operations · Info category: FINANCIAL_RISK |
| Climate Change and Adaptation |
|
|
| 750 · Description: Climate change and disasters · Info category: OPERATIONAL_RISK · 751 · Description: Impact on the environment · Info category: OPERATIONAL_RISK · 1717 · Description: ESG risk · Info category: STRATEGIC_RISK · 1719 · Description: Climate change and disasters · Info category: STRATEGIC_RISK |
| Shortage of resources/raw materials in construction |
|
|
| 728 · Description: Volatility in the industry in which the company operates · Info category: STRATEGIC_RISK · 751 · Description: Impact on the environment · Info category: OPERATIONAL_RISK · 1717 · Description: ESG risk · Info category: STRATEGIC_RISK |
| Community Participation and Impact on Quality of Life |
|
|
| 751 · Description: Impact on the environment · Info category: OPERATIONAL_RISK · 1717 · Description: ESG risk · Info category: STRATEGIC_RISK |
| Human Resource Management and Occupational Safety |
|
|
| 749 · Description: Safety, occupational health, and working environment · Info category: OPERATIONAL_RISK · 1717 · Description: ESG risk · Info category: STRATEGIC_RISK · 753 · Description: Impact on human rights · Info category: OPERATIONAL_RISK |
| Governance and Transparency |
|
|
| 759 · Description: Corporate Governance · Info category: COMPLIANCE_RISK · 1717 · Description: ESG risk · Info category: STRATEGIC_RISK |
| Compliance with Personal Data Protection Law |
|
|
| 756 · Description: Change in laws and regulations · Info category: COMPLIANCE_RISK · 1717 · Description: ESG risk · Info category: STRATEGIC_RISK |
| Climate Change Risks |
|
|
| 750 · Description: Climate change and disasters · Info category: OPERATIONAL_RISK · 751 · Description: Impact on the environment · Info category: OPERATIONAL_RISK · 1717 · Description: ESG risk · Info category: STRATEGIC_RISK |
| Risks from evolving information technology and cyber threats | Currently, information technology plays a crucial role in business operations, with technology being applied to various work processes to promote greater agility and speed. However, the use of information technology also presents opportunities and risks stemming from cyber threats. Consequently, the risk of cyber threats is considered highly significant and has a direct impact on the company's operations. Should problems arise concerning the company's information technology systems or unauthorized access to personal data held by the company, it would inevitably affect the company's operations and reputation. | Information technology risks and cyber threats may result in the disruption of the company's operational systems, project delays, damage to critical data and customer privacy, as well as damage to the reputation and confidence of investors and stakeholders. Furthermore, it may increase the costs of system improvements and problem resolution. | The company therefore has an information technology security policy to ensure that its personnel, users, executives, and relevant individuals are aware of the importance of information technology security. This policy defines information technology security measures, including improving computer network systems to ensure availability and prevent failures of network and server systems, thereby enabling continuous system operation. Strict security control measures are implemented, such as computer security systems (Firewall), antivirus systems (Antivirus), defining data access rights according to the nature of work of each department, and establishing a network with a data backup center to support emergencies and ensure continuous business operations, among others. This is to ensure that the company's information technology and computer systems operate without impacting business operations, and that the systems are used correctly in compliance with the Computer-Related Crime Act, the Personal Data Protection Act, and other relevant laws, as well as to prevent threats that could cause damage to the company. | 732 · Description: Changes in technologies · Info category: STRATEGIC_RISK · 744 · Description: Information security and cyber-attack · Info category: OPERATIONAL_RISK · 1717 · Description: ESG risk · Info category: STRATEGIC_RISK · 1720 · Description: System disruption risk · Info category: OPERATIONAL_RISK |
| International War |
|
|
| 731 · Description: Policies or international agreements related to business operations · Info category: STRATEGIC_RISK |
| Climate Change and Disaster Occurrence (Earthquake) |
|
|
| 750 · Description: Climate change and disasters · Info category: OPERATIONAL_RISK · 1719 · Description: Climate change and disasters · Info category: STRATEGIC_RISK |